
Prediction: This Will Be Intel’s Stock Price After 1 Year (Hint: It Implies a Nice Jump)

 Prefer us on Google


Shares of Intel (INTC -1.52%) delivered incredible gains to investors in the first half of 2026, but have seen significant volatility in recent months.
As it turns out, Intel stock has retreated 51% since the beginning of July. The past few days have been even more brutal for Intel investors, with the stock plunging big time following the release of its third-quarter results on Oct. 29. However, Intel's pullback could be an opportunity for savvy investors to buy a top semiconductor stock at an attractive valuation, especially given its solid upside potential.
Let's take a closer look at Intel's prospects and valuation to check how much upside it could deliver over the coming year.
Image source: Getty Images.
Intel's data center business will drive stronger growth in 2027
When Intel released its Q3 results, the company reported a solid 21% increase in revenue from the year-ago period to $16.5 billion. The company's non-GAAP earnings per share (EPS) jumped by an incredible 126% from the year-ago period to $0.52.
Intel delivered such impressive growth despite a 5% decline in revenue from its client computing and physical artificial intelligence (AI) business segment. It is worth noting that this business is a key source of revenue for Intel, accounting for nearly half its top line in Q3. The ongoing weakness in the PC market, along with Intel's market share losses to Advanced Micro Devices, explains why Chipzilla's sales in this segment dropped last quarter.
The bad news for Intel investors is that the PC market's decline is here to stay. Counterpoint Research notes that PC sales dropped by 21% last quarter, and the Q4 decline is likely to be steeper at 27%. Higher costs of memory and other components are taking a toll on this market. The positive news is that Intel expects the PC decline to ease in 2027, with unit shipments predicted to drop by 10%.
However, the biggest takeaway from Intel's quarterly report is the impressive growth in the company's data center business. Its data center and AI revenue increased by an incredible 78% from the year-ago period to $7.3 billion, helping lift the company's top and bottom lines. Looking ahead, Intel expects the data center business to sustain its solid momentum in 2027, driven primarily by the healthy demand for server central processing units (CPUs).
Intel noted on the latest earnings call that its Granite Rapids server CPUs have "become one of the fastest ramping server products." Meanwhile, the company is already witnessing strong demand for its first Intel 18A server CPU codenamed Clearwater Forest, which will start shipping next year. Overall, Intel's server CPU business seems poised for healthy growth in 2027, driven by partnerships with major AI infrastructure players such as Oracle.
Intel points out that the total addressable market (TAM) for server CPUs could increase from the current $40 billion to more than $200 billion over the next five years, as these chips are used to handle agentic AI and inference workloads. As such, I won't be surprised to see Intel's DCAI business sustain solid growth in 2027 and beyond, boosting the company's overall growth as it starts accounting for a larger share of its business.
An attractive valuation and solid earnings growth make the stock a no-brainer buy
Intel trades at 37 times forward earnings, which is quite attractive for a company that delivered triple-digit earnings growth last quarter. What's more, even though Intel's Q4 guidance turned out to be weaker than expected, investors will do well to note that the company will still deliver respectable earnings growth.
Intel's Q4 non-GAAP EPS guidance of $0.25 is significantly lower than the consensus estimate of $0.43, but it implies a 66% increase from the year-ago period. For the full year, analysts are expecting Intel's EPS to increase by a whopping 254% to $1.49. Analysts expect Intel's EPS growth to slow down to 20% in 2027, but that may not be the case due to potential price hikes in server CPUs.
As a result, Intel could step on the gas over the coming year. Even Wall Street is bullish about the stock's trajectory, with Intel's 12-month median price target of $88 implying 41% upside. This AI stock could indeed deliver solid gains by outpacing Wall Street's growth expectations, thereby encouraging the market to reward it with a premium valuation.
After all, Intel trades in line with the iShares Semiconductor ETF, an exchange-traded fund that tracks the semiconductor industry and has a price-to-earnings ratio of 37. So, it seems like a good idea to accumulate Intel while it remains beaten down, as its improving data center prospects could supercharge the stock in 2027.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like

Stacks (STX) outlook for 2027: What could drive STX demand?
Guterres Calls for Additional Taxes on Energy Companies
Cities and States Representing 60% of U.S. Economy Commit to Collaborate with the UN on Tracking Carbon Emissions
Startup Voya Energy Proposes Solution to Replace Noisy Diesel Generators in Data Centers
55 million ZETA to be destroyed, ZetaChain continues to operate after shutdown announcement
SK Group Executives Hold Meeting from 12th to 14th to Discuss Semiconductor, AI, and Energy Business Strategies
Indian Stock Market Rebounds, Becomes Safe Haven Amid AI Stock Sell-off

Barclays: Japan's Import Prices Rise 24.8% in October

CNOOC Discovers High-Yield Oil and Gas Well in Bohai Sea with Daily Production of 800,000 Cubic Meters
Aave V3.8 Launches, Covering 15 Markets with Reentrancy Protection
唐华斑竹: Avalanche Chain May Become the Standard for Security Tokenization

Decrypt Becomes First News Publisher to Offer Perps Trading, Powered by Solana's Phoenix
Moody's Projects Global Credit Deterioration by 2027 and Warns of the Impact of Rates and AI
What Is Elysium Crypto? The Hyperliquid Layer 2, Gas Fees, and Token Confusion Explained
Learn what Elysium is, why it uses HYPE for gas, how KNTQ buybacks are designed, and how to distinguish bridge TVL from actual DeFi activity.
From Sidechains to zk-Rollups: Tacit Chain Aims to Redefine Payments with Default Privacy
Midterm Election Risks Disrupt Helix AI Infrastructure Project, Increasing Uncertainty for Samsung Investments
European Natural Gas Futures Prices Exceed €85
Moody's Raises India's Economic Growth Forecast to 7%
Immutable Chain's Transition to OP Stack: What Changes for Users
Two Carbon Capture Standards Released
US Absence from UN Climate Summit, Trump Calls Global Warming a Hoax
ETH Burn Rate Fails to Keep Up with Issuance, Is Vitalik Starting to Discuss Value Storage?
Ethlabs Suggests Delaying Hoodi Testnet Fork Date, External Audit Expected to be Released Before November 16
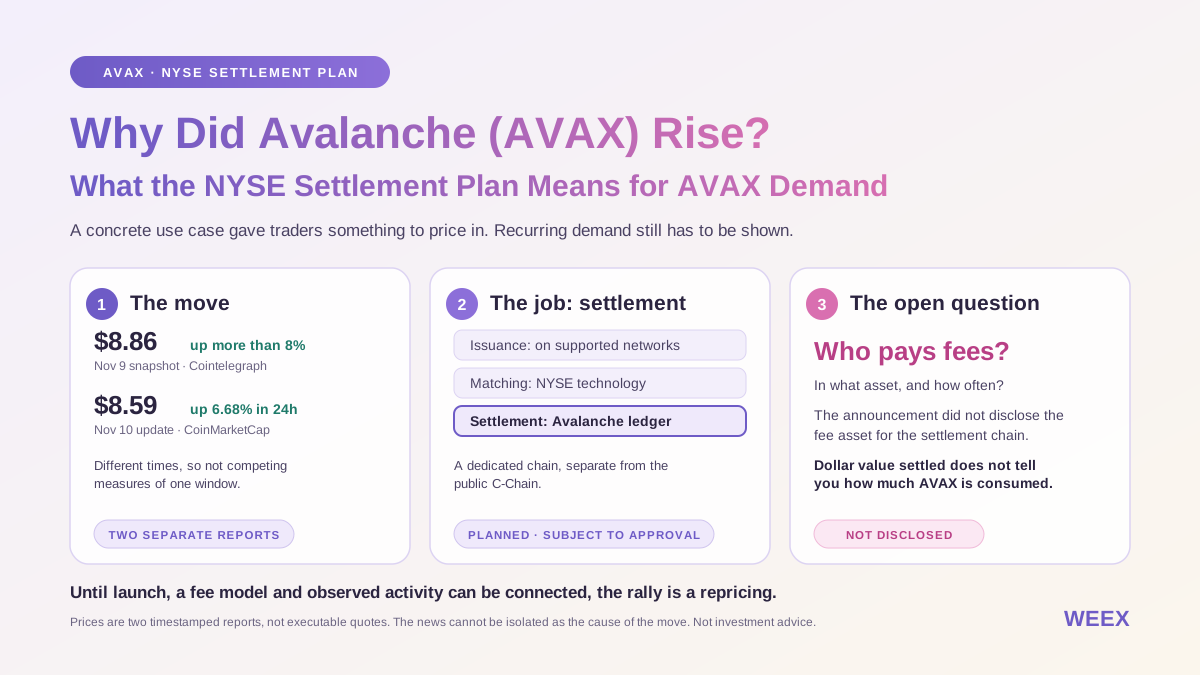
Why Did Avalanche (AVAX) Rise? What the NYSE Settlement Plan Means for AVAX Demand
See why Avalanche (AVAX) rallied after the NYSE settlement announcement, how the dedicated chain would work, and what could create demand for AVAX.
How to Resolve Data Center Controversies? This U.S. State Wants to Tokenize Computing Power to Share Benefits with Residents
Wall Street Morning Briefing: Market Soars on Oil Prices and AI Recovery, Nvidia Falls Alone, Data Centers Become Political Regulation Focus, CPI Lacks Year-on-Year Comparison Adds Variables

Ethereum's 2028 Challenge: Quantum Resistance Roadmap Hits Release Bottleneck
Understanding the DEX 'Hyperliquid': A Practical Workshop|Japan Digital Economy Federation

Envision Star River Base Completed in One Year with 120MW Capacity at One-Fifth the Cost of Similar U.S. Projects
AI Data Centers Are Buying Used Jet Engines as New Power Turbines Take Six Years
Stacks (STX) outlook for 2027: What could drive STX demand?
Guterres Calls for Additional Taxes on Energy Companies
Cities and States Representing 60% of U.S. Economy Commit to Collaborate with the UN on Tracking Carbon Emissions
Startup Voya Energy Proposes Solution to Replace Noisy Diesel Generators in Data Centers
55 million ZETA to be destroyed, ZetaChain continues to operate after shutdown announcement
SK Group Executives Hold Meeting from 12th to 14th to Discuss Semiconductor, AI, and Energy Business Strategies
Latest articles


Latest coin listings on WEEX


