AMD Stock Ahead of Q3 2026 Earnings: Revenue, AI Demand, and Key Risks to Watch

 Prefer us on Google


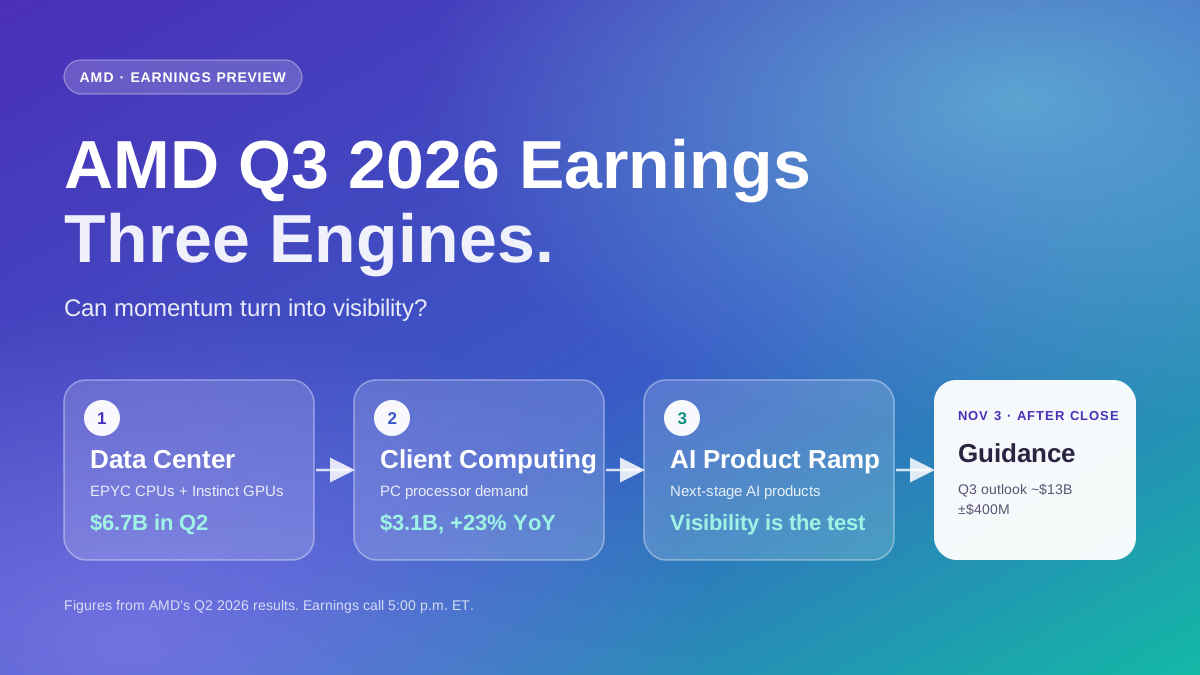 AMD is scheduled to report fiscal third-quarter 2026 results after the market closes on Tuesday, November 3. The central question for AMD stock is whether the company can show that its exceptional data-center growth is continuing while also giving credible evidence that future AI product ramps will convert into durable revenue, margins, and customer demand.
Our view is that AMD’s Q3 report needs to do more than repeat a strong AI narrative. The company has already set a high bar through rapid data-center expansion and a Q3 revenue outlook of about $13 billion. The more important test is whether the results and next-quarter guidance show broad, sustainable execution rather than expectations being carried by future product potential alone.
When Is AMD Reporting Q3 2026 Earnings?
AMD has announced that it will release fiscal Q3 2026 results on Tuesday, November 3, after the U.S. market closes. Management’s earnings call is scheduled for 5:00 p.m. Eastern Time, or 2:00 p.m. Pacific Time.
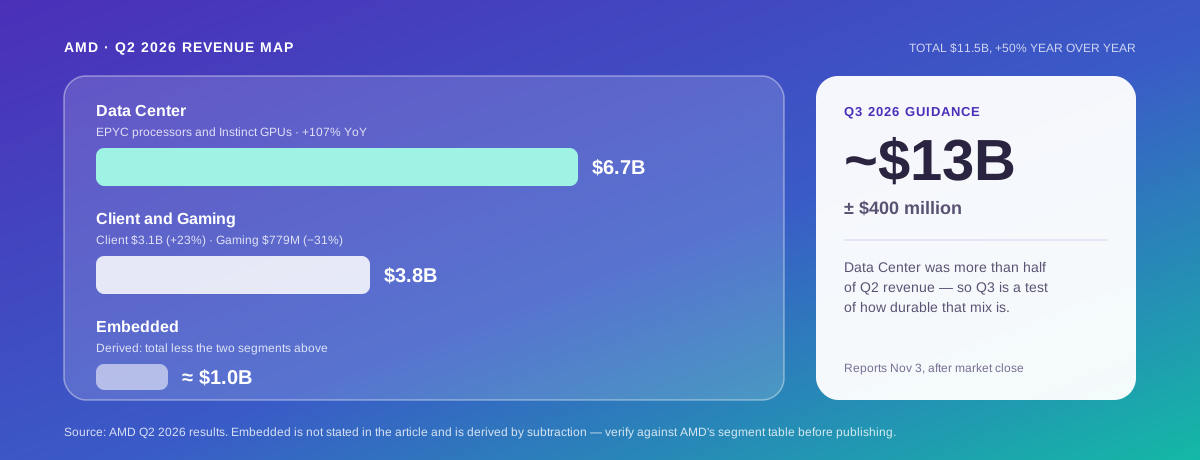
The event arrives after a strong Q2. AMD reported revenue of $11.5 billion, up 50% year over year, while Data Center revenue reached $6.7 billion, up 107% year over year. The company said this was driven by demand for EPYC processors and Instinct GPUs. For Q3, AMD guided to approximately $13 billion in revenue, plus or minus $400 million.
That combination explains why the earnings setup is demanding. AMD does not only need to report growth. It needs to show that growth remains robust enough to support the expectations created by its data-center momentum and expanding AI roadmap.
The AMD Earnings Question Is a Revenue-Quality Question
A headline revenue beat can be positive, but it does not answer every question surrounding AMD stock. Investors will want to know where the growth came from, whether it is profitable, and whether the company’s next-quarter outlook supports the same trajectory.
The most useful way to read AMD’s report is as a revenue-quality check across four areas:
| Area | What to Watch | Why It Matters |
|---|---|---|
| Data Center | EPYC processor and Instinct GPU demand | This segment is the main engine behind AMD’s current AI and server-growth narrative |
| Gross Margin | Whether product mix supports or pressures profitability | Higher revenue is more valuable when it also improves earnings quality |
| Client and Gaming | PC processor demand versus semi-custom and gaming trends | It shows whether growth is broad-based or concentrated in one segment |
| Forward Guidance | Q4 revenue outlook and commentary on product ramps | Markets value the next stage of demand, not only the reported quarter |
This framework is especially important because data-center growth can make AMD’s total revenue look stronger even when other segments are mixed. That does not necessarily mean the quarter is weak. It means investors should distinguish between a concentrated AI-led quarter and broad execution across the portfolio.
Data Center Remains the Key AMD Stock Driver
AMD’s Data Center segment is likely to be the most closely watched part of the report. In Q2, the segment generated $6.7 billion in revenue—more than half of company-wide revenue—and grew 107% from the prior-year period.
That scale changes the way AMD earnings should be interpreted. The company is no longer judged only as a PC and gaming chipmaker with AI upside. Data-center demand has become central to both its operating performance and the expectations embedded in AMD stock.
Investors will therefore look for more than a broad statement that demand remains healthy. They will want management to clarify the balance between server CPU demand, AI accelerator demand, customer deployments, and the timing of new product availability.
A favorable report would show that the existing data-center business remains solid while the next generation of AI products is progressing on schedule. A less convincing report would leave investors with strong current numbers but little visibility into whether the next stage of growth can meet elevated expectations.
-- Price
Why AI Demand Must Be Separated From AI Expectations
The phrase “AI demand” can hide several different questions. There is demand for server CPUs that support AI workloads, demand for GPU accelerators, demand for complete rack-scale systems, and demand that has been announced but has not yet reached material revenue.
For AMD, this distinction matters. The company’s AI opportunity is real, but investors should separate what is contributing to reported revenue today from what is expected to contribute in future quarters. Product roadmaps, partnership announcements, and customer interest can all be strategically meaningful without producing the same immediate financial effect.
The Q3 call will be more useful if management clarifies:
- Which AI products are already contributing materially to revenue.
- How demand is evolving across existing Instinct GPUs and server processors.
- Whether product availability, supply, memory, or customer deployment schedules could affect the pace of future growth.
- How the company expects the mix of CPUs, accelerators, and integrated systems to influence margins.
This is the difference between a narrative-driven earnings read and an operational one. Investors do not need every AI project to contribute immediately. But they do need a clear path from product development to volume deployment and revenue recognition.
Client Computing Can Still Matter to the AMD Earnings Story
AMD’s Client and Gaming segment generated $3.8 billion in Q2 2026. Within that segment, Client revenue was $3.1 billion, up 23% year over year, while Gaming revenue was $779 million, down 31% year over year because of lower semi-custom revenue.
That split is worth watching in Q3. Strong client-processor demand can help diversify AMD’s growth beyond the data center. But weaker gaming or semi-custom demand can pull in the other direction. The key is not that every business line must move identically; it is whether the overall portfolio supports AMD’s revenue and margin profile as the data-center mix expands.
This also makes AMD different from a pure-play AI infrastructure story. Its earnings report contains signals about enterprise computing, PCs, gaming, embedded products, and AI data centers. The most useful interpretation comes from understanding how those businesses fit together rather than treating every result as a single AI verdict.
What Could Change the Market’s View After November 3?
AMD stock may react to the gap between reported results and the market’s prior expectations. That means the forward-looking discussion can be as important as the Q3 figures themselves.
A constructive earnings read could include revenue near or above the upper end of AMD’s guidance range, continued Data Center strength, stable or improving gross-margin commentary, and a Q4 outlook that supports confidence in the product ramp. Clear detail around customer adoption would strengthen that case.
A more cautious reaction could follow if growth remains strong but guidance suggests a slower pace ahead, if margins do not reflect the higher-value mix investors expect, or if management provides limited visibility into AI-product timing. In a market already debating the durability of AI infrastructure spending, uncertainty can matter as much as the reported result.
The crucial question is not whether AMD can post growth. It is whether the company can explain why that growth remains durable as the comparison base becomes more demanding.
AMD Stock and the WEEX TradFi Prediction Event
The WEEX TradFi Prediction Event runs from October 6 through November 6, 2026, placing AMD’s November 3 earnings within the active campaign period. Users who register can take part in eligible earnings predictions using activity points, with a minimum of one point per prediction.
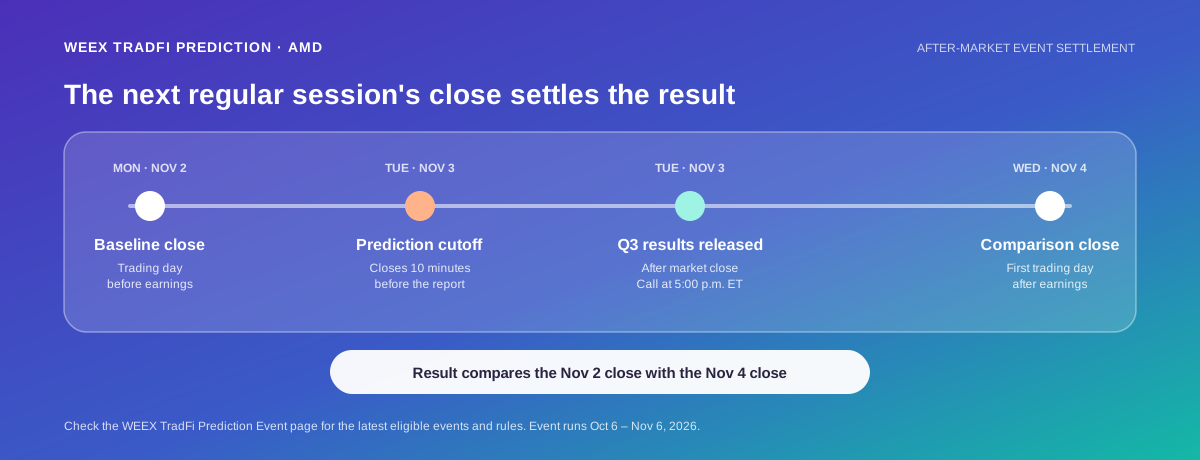
For each eligible earnings event, the prediction channel closes 10 minutes before the scheduled report. The result is based on the comparison between the closing price on the trading day before earnings and the close on the first trading day after earnings. For AMD’s after-market release, that means the next regular trading day’s closing reaction is the relevant result—not only the initial after-hours move.
Users should review the latest eligible-event list, task requirements, and activity rules on the event page before participating.
A Practical Earnings Checklist for AMD
Before AMD reports, readers can reduce noise by writing down the company’s own Q3 outlook—approximately $13 billion in revenue, plus or minus $400 million—and then comparing the actual report against that starting point.
After the release, the most useful questions are:
- Did AMD meet or exceed its own revenue outlook?
- Did Data Center growth remain strong, and did management explain the mix between CPUs and AI accelerators?
- Did gross-margin commentary support the quality of growth?
- Did Client revenue continue to offset weaker Gaming trends?
- Did Q4 guidance make the next AI product ramp clearer or more uncertain?
This checklist is more useful than reacting to a single earnings-per-share headline. It turns a complex report into a set of linked operating questions.
WEEX Editorial View: AMD Must Convert AI Momentum Into Visibility
AMD’s opportunity is not in doubt. Its Q2 Data Center results showed that the company has already become a meaningful participant in the AI infrastructure buildout. But the market has moved past broad excitement about AI exposure. It now wants evidence of execution, supply readiness, profitable mix, and forward visibility.
That is why AMD’s November 3 report matters. The most important outcome would not merely be another large growth percentage. It would be a report that connects present demand with a believable path through the next product cycle. For AMD stock, the difference between momentum and durable value will be found in that connection.
FAQs
1. When Is AMD Reporting Q3 2026 Earnings?
AMD is scheduled to report fiscal Q3 2026 results after market close on Tuesday, November 3, 2026.
2. What Is AMD’s Q3 2026 Revenue Guidance?
AMD guided to Q3 2026 revenue of approximately $13 billion, plus or minus $400 million.
3. Why Is Data Center Revenue So Important for AMD Stock?
AMD’s Data Center segment generated $6.7 billion in Q2 2026, up 107% year over year. It is the company’s largest reported growth engine and a key indicator of server and AI demand.
4. How Does the WEEX TradFi Prediction Event Settle AMD Earnings Predictions?
For eligible events, the result compares the closing price on the trading day before earnings with the closing price on the first trading day after earnings. Check the activity page for the latest event eligibility and rules.
Sources
- AMD: Fiscal Q3 2026 Results Announcement — accessed October 15, 2026
- AMD: Q2 2026 Financial Results — accessed October 15, 2026
- WEEX TradFi Prediction Event — activity period: October 6 to November 6, 2026
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Bitwise CIO: Choose Your Own Adventure, All Paths Lead to Bitcoin
Tether launches offline AI speech model for smart glasses and robots
"Japan's Barrier is Not Culture but Local Investment" - Huobi Co-founder Du Jun Discusses Regulations, Stablecoins, and Expansion in Asia
Analyst Who First Predicted September Rate Hike: Fed to Hold Steady in October, May Hike 50 Basis Points in December
Slash Card Now Available for Payment with USDC, Open to the Public
Will Stablecoins Become 'Financial Infrastructure'? - A Discussion with Circle on Arc and the Current State of Digital Payments in Japan (10/21 19:30 @ Gentosha)
StandX Co-founder Announces Halt to Token Generation Event
Uncertainty in Trump’s Policies Drives Central Banks to Reallocate Gold, London’s Gold Reserves Near 10,000 Tons
[Exclusive] Coinbase Transaction Data Shows 100 Million Trades Misrepresented... Data Analysis Firm Corrects Errors
ASIC Seeks Public Consultation on Capital, Custody, and Trading Rules for Crypto Platforms, Set to Launch in 2027
JANUSZ KRYPTO: Is My Ledger Safe? Spyware in Wallets and Stolen Millions
X-Agent Builds Onchain Personal AI Assistant
Solana to Update Its Consensus Mechanism on October 21
The Importance of Analyzing Trading Strategies and Stop-Losses by Sam Price
Glassnode: Bitcoin capped by ETF outflows, inflation pressure
Bitcoin Fog operator’s conviction upheld without Chainalysis disclosing source code
Underground Crypto Farm Discovered at Automobile Plant in Ulyanovsk
Meta Stock Earnings: What to Watch in Meta Platforms’ Q3 2026 Results
Meta reports Q3 2026 results on October 21. See the advertising, AI spending, margin, and guidance signals that could move META stock.
Operation Blackout: FBI Claims $17 Billion Seized
Federal Reserve to Further Tighten Policy, September Rate Hike Not a One-Time Action
Nine Major Banks Accused of De-Banking Practices, OCC Releases Final Report
Awaiting the Release of the U.S. Inflation Report and Its Impact on Bitcoin
PONS Remains the Highest Revenue Project in the Robinhood Chain Ecosystem, Potentially Leading the Market
Ethereum ETF Funds Break Out of Outflow Series with Inflows of $24.8 Million
SBF Seeks Supreme Court Review to Overturn $11 Billion Forfeiture Order
Kraken to Acquire Saldo Bank
Funding Souq Secures Strategic Investment from Foodics
DBS Bank: Core CPI Expected to Slow to 0.2%
Anthropic Opens Office in Singapore and Signs Memorandum of Understanding
The NFT Losses That Hong Kong Star Fang Lishen Dares Not Speak Of: Unveiling Another Side of the Celebrity Influx
Bitwise CIO: Choose Your Own Adventure, All Paths Lead to Bitcoin
Tether launches offline AI speech model for smart glasses and robots
"Japan's Barrier is Not Culture but Local Investment" - Huobi Co-founder Du Jun Discusses Regulations, Stablecoins, and Expansion in Asia
Analyst Who First Predicted September Rate Hike: Fed to Hold Steady in October, May Hike 50 Basis Points in December
Slash Card Now Available for Payment with USDC, Open to the Public
Will Stablecoins Become 'Financial Infrastructure'? - A Discussion with Circle on Arc and the Current State of Digital Payments in Japan (10/21 19:30 @ Gentosha)